

Most UK lenders ask for a personal guarantee when financing a new franchise, because a start-up has no trading history to lean on. The exception comes with established, resale or multi-unit franchises, where strong security, cashflow or Growth Guarantee scheme backing can soften that requirement. Gov sets out the legal basics, and resources from franchise directories can help you match opportunities to the right funding route.
What is a personal guarantee under UK law?
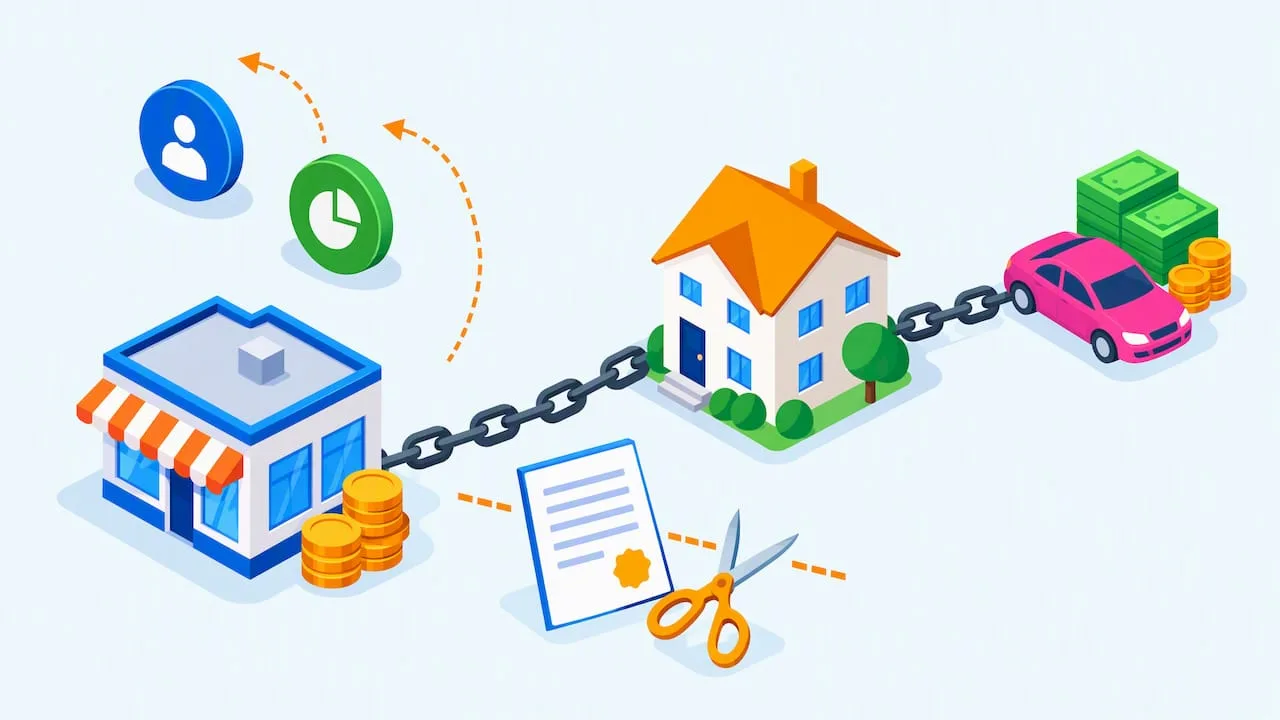
A personal guarantee is a legally binding agreement that makes a director or business owner personally liable for repaying a company’s debt if the business defaults, and lenders can pursue personal assets including homes, savings and cars to settle that debt, according to gov.uk guidance. Guarantees come in two broad forms: secured, where specific assets such as property are named as collateral, and unsecured, where the guarantee simply sits behind the debt without naming particular assets upfront.
Many franchise loan agreements use joint and several liability wording when more than one director signs, which means a lender can pursue any single guarantor for the full outstanding balance rather than splitting the claim evenly. Read the clauses carefully before signing, since the wording often extends beyond the original loan amount to interest, legal costs and any variations to the facility.
Assets a lender can realistically target include:
- The family home, where a charge can be registered against it
- Savings accounts and investment portfolios held personally
- Vehicles and other high-value personal property
- Future income, through earnings attachment in some enforcement routes
Understanding this taxonomy matters before you negotiate terms, because a guarantee capped at a fixed sum behaves very differently from one that leaves your full personal wealth exposed.
How lenders use personal guarantees in franchise financing
Lenders ask for personal guarantees mainly to reduce their credit risk on lending that would otherwise be unsecured, particularly when a franchise has limited trading history and few business assets worth taking as collateral. For a franchise specifically, the request typically follows a predictable pattern:
- Start-up single-unit franchises almost always attract a guarantee request, since the business has no accounts, no established cashflow and often no property of its own to secure against.
- Multi-unit expansion by an existing, profitable franchisee can sometimes avoid a full guarantee, because the lender can point to real trading figures and existing business assets as security instead.
- Franchise resale purchases sit somewhere between the two: lenders look at the outgoing owner’s historical performance, but still usually want the incoming owner personally on the hook until the new operation proves itself.
Government-backed schemes change the calculation only partly. Under the Growth Guarantee scheme, the government provides lenders with a substantial guarantee against the outstanding balance, but the business remains 100% liable and lenders may still take personal guarantees on top of that support. The one restriction built into the scheme is that lenders cannot take your principal private residence as security under its rules, which is a meaningful limit even though it does not remove the guarantee requirement entirely. Banks reviewing franchise applications also weigh trading history and available security heavily, a point worth reading up on in our guide to what UK banks expect from franchisee financing.
What happens if you default with a personal guarantee in place
Signing a personal guarantee is not a formality you forget about once the loan is approved. If a franchise defaults, the lender’s enforcement route typically follows a sequence rather than jumping straight to the most severe outcome.
- The lender issues formal demand for repayment under the guarantee terms
- Unpaid demands can lead to a county court judgment against you personally
- A judgment can be used to register a charge against your home or other property
- Continued non-payment can ultimately lead to personal bankruptcy proceedings
Many lenders require independent legal advice and, in some cases, solicitor confirmation that this advice was given before a personal guarantee is accepted, according to the British Business Bank’s guide to personal guarantees. That requirement exists precisely because the consequences of signing can be severe and permanent.
Directors also carry separate duties that survive a franchise’s financial trouble. If the company becomes insolvent, directors can face personal liability for wrongful trading or fraudulent trading, and gov.uk’s director duties guidance is clear that specialist advice is needed the moment insolvency becomes a realistic risk, separate from whatever the personal guarantee itself says.
One detail catches out more franchisees than almost any other: a guarantee does not expire when you resign as director or sell your shares. It stays live until the lender issues an express written release, so always confirm in writing, before any exit or sale, that the guarantee has been formally discharged and recorded against the loan documents. Our guide to assessing franchise risk covers this alongside other due diligence steps worth working through before you commit.
How lenders decide and what you can negotiate
Lenders build their view of your risk from a handful of recurring factors: time the business has been trading, cashflow strength and forecasts, your personal credit history, and whatever collateral or security already sits behind the loan. A self-employed applicant with thin paperwork can strengthen their position considerably by assembling clear proof of income and deposit funds, a process covered well in Prosper Home Loans’ guidance on proving deposits as a self-employed buyer, much of which applies equally to franchise lending conversations.
None of this means guarantee terms are fixed. The parts most worth pushing back on include:
- A capped guarantee limited to a fixed sum rather than the full facility
- A time-limited or sunset clause that lapses after a set trading period
- Specific asset carve-outs, such as excluding the family home
- A clear release trigger tied to loan repayment milestones or refinancing
Pro Tip: Ask your lender in writing, before you sign anything, exactly what would trigger a release of the guarantee, and get that answer added to the facility letter.
Many lenders insist on evidence that you took independent legal advice before accepting a guarantee, which adds formality but also protects you, since a solicitor can flag wording that extends liability further than you intended. Our piece on preparing a funding package as a new franchise owner walks through how to approach these conversations with lenders from a position of strength.
Alternatives that reduce or avoid a personal guarantee
A personal guarantee is often the only practical way to access unsecured lending for founders without business assets to offer, but it is not the only route into franchise finance. Several options can reduce or avoid personal exposure depending on your circumstances:
- Secured lending against business assets, where equipment, stock or commercial property stand behind the loan instead of your personal wealth.
- Invoice or asset finance, which draws on receivables or equipment value rather than a personal covenant.
- Start Up Loans, a government-backed unsecured personal loan scheme aimed at new businesses, though it still carries personal liability by design.
- Leasing and hire purchase, useful for vehicles or equipment where the asset itself is the lender’s security.
- Equity or angel investment and grants, which avoid debt and guarantees entirely but mean giving up a stake or meeting strict eligibility criteria.
British Business Bank guidance notes that genuinely guarantee-free lending products tend to be reserved for well-established businesses with strong trading records, so a brand-new franchise is unlikely to qualify straight away. As covered above, the Growth Guarantee scheme improves a lender’s own risk position but does not remove their discretion to still ask you for a personal guarantee. Our guide to franchise loan types breaks down which of these options tend to suit which stage of franchise ownership.
Legal steps to take before you sign
Before signing anything, instruct a solicitor who is independent of the lender and the franchisor, not one recommended by either party. Many lenders will ask for written confirmation that this advice was given, and some require the solicitor to witness your signature directly.
- Confirm the solicitor has reviewed the exact wording of the guarantee, not a summary
- Ask whether Etridge or O’Brien principles apply to your situation, particularly if a spouse or partner is also being asked to guarantee the debt
- Request a capped liability figure in writing wherever the lender will agree to one
- Request a sunset clause or an explicit release trigger tied to loan performance
Lenders and solicitors must take reasonable steps to ensure third-party guarantors understand the risks they are taking on, with Etridge and O’Brien case principles underpinning requirements for lenders to warn guarantors and ensure independent advice is given where undue influence might arise.
Law Society of Scotland
This matters most where a partner or family member is asked to guarantee a debt they have no direct stake in running. Our guide to franchisee responsibilities covers the wider set of legal obligations worth understanding before you commit to a franchise agreement.
Your next steps before approaching a lender
The practical verdict stands: expect a personal guarantee on most new franchise lending, and make capping it or limiting its duration your top negotiating priority. Before any finance conversation, request the guarantee terms in writing, instruct an independent solicitor to review them, and use Franchiselocal’s resources to compare funding routes against franchise investment levels. Whatever you agree, insist on a documented release once the guarantee’s purpose has been served.
How we help you prepare for the finance conversation
We built our directory so you can filter franchise opportunities by investment level before you ever approach a lender, which makes the guarantee conversation far more predictable. Browse loans and financial franchise categories alongside our funding guides to match the right opportunity to the finance you can realistically secure, and start your search on our UK franchise directory.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Can I take out a business loan to buy a franchise?
Yes, UK lenders including high street banks and alternative finance providers regularly lend for franchise purchases, though most will ask for a personal guarantee alongside the usual business plan and financial projections. The exact terms depend heavily on your trading history, available security and the franchise’s own track record.
Are COVID business loans still available?
No, the COVID-era support schemes such as the Bounce Back Loan Scheme and CBILS closed several years ago and have been replaced by ongoing programmes like the Growth Guarantee scheme. That scheme still requires the business to carry full liability for the debt, with the government guarantee covering the lender’s loss rather than yours.
Who offers guarantor loans in the UK?
Guarantor loans, where a third party agrees to repay if you cannot, are offered by a range of specialist consumer lenders rather than mainstream banks, and they operate differently from the personal guarantees used in franchise business lending. For franchise finance specifically, the guarantee usually comes from the franchisee or director themselves rather than an outside guarantor.
What is a company limited by guarantee in the UK?
A company limited by guarantee is a structure typically used by non-profits and clubs, where members commit to pay a nominal sum if the company winds up, rather than holding shares. It is a different concept entirely from a personal guarantee on a business loan, and it is rarely the structure used by trading franchise businesses.
Do I need a personal guarantee to get franchise funding?
For most new, single-unit franchises, yes, a personal guarantee is the practical price of accessing unsecured lending, as founders without substantial business assets have few other ways to reassure a lender. Established, multi-unit or well-secured franchise purchases have more room to negotiate a capped, time-limited or asset-excluded version of the guarantee instead.